Medicare Open Enrollment 2027: Part D Cap Rises to $2,400 and What Else Changes Before Dec. 7

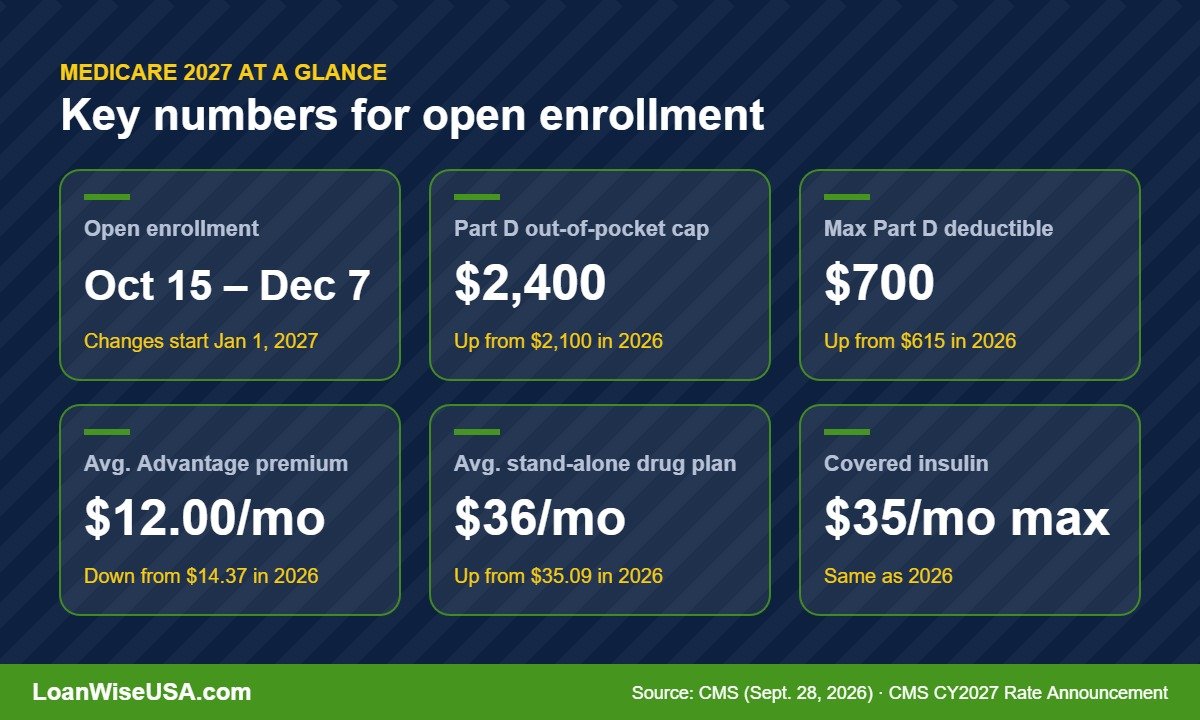
Quick answer: Medicare open enrollment for 2027 coverage runs from October 15 to December 7, 2026, and any change you make takes effect January 1, 2027. The biggest change is in Part D: the yearly out-of-pocket cap on covered drugs rises from $2,100 to $2,400, and the maximum deductible rises from $615 to $700. CMS also expects the average Medicare Advantage premium to fall to about $12 a month, while stand-alone drug plans average about $36 a month. Because individual plans change every year, compare your own plan before December 7 instead of letting it renew automatically.
Every fall, more than 70 million people with Medicare get a chance to switch health and drug plans. Many people skip it and let their plan roll over. That is often a mistake, because plans can change their premiums, deductibles, drug lists and pharmacy networks each January. This guide explains what is changing for 2027, what the official numbers are, and how to check your options in about an hour.
When is Medicare open enrollment for 2027?
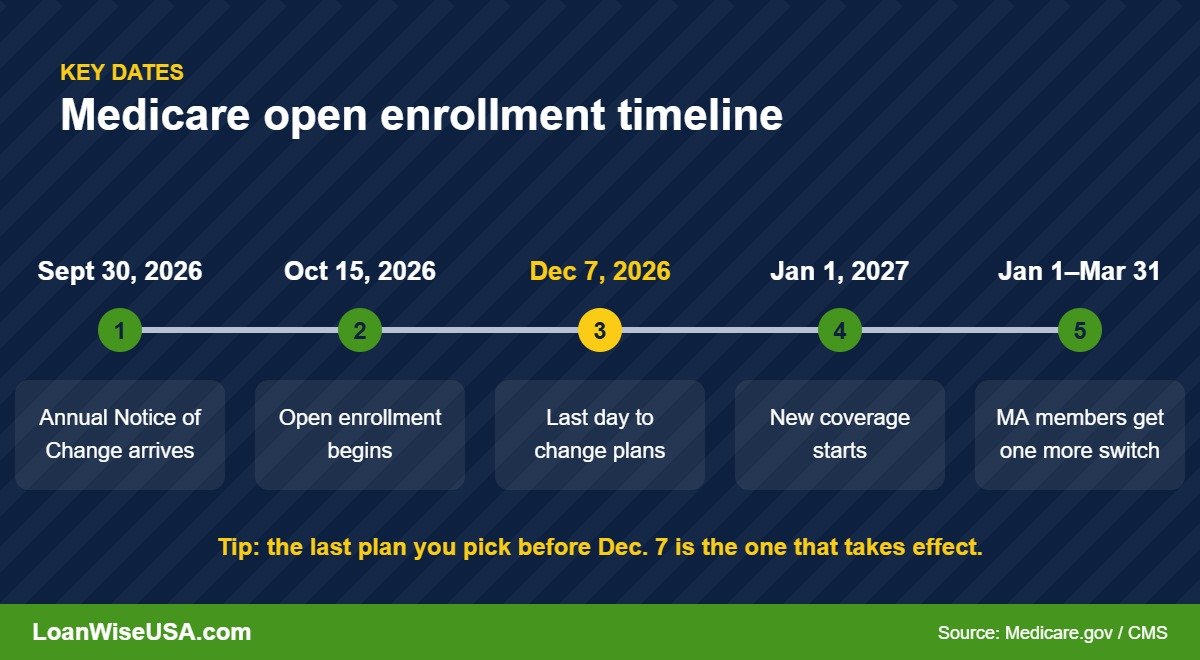
The Medicare Annual Enrollment Period runs from Wednesday, October 15, 2026, through Sunday, December 7, 2026. You can change plans as many times as you like during this window. The last plan you choose before the deadline is the one that starts on January 1, 2027.
Under 65 and buying your own coverage? That is a separate window: see our guide to ACA open enrollment 2027, which runs through January 15.
There is also a second, smaller window. If you are already in a Medicare Advantage plan on January 1, the Medicare Advantage Open Enrollment Period from January 1 to March 31, 2027 lets you make one switch: to a different Medicare Advantage plan, or back to Original Medicare (and you can add a Part D drug plan at the same time).
What is changing in Medicare Part D in 2027?
The Part D redesign under the Inflation Reduction Act capped yearly out-of-pocket drug costs starting in 2025. The cap is indexed, so it rises a little each year. Here are the standard benefit numbers set by CMS in its 2027 Rate Announcement:
| Part D item | 2026 | 2027 |
|---|---|---|
| Annual out-of-pocket cap on covered drugs | $2,100 | $2,400 |
| Maximum standard deductible | $615 | $700 |
| Covered insulin (per month’s supply) | $35 max | $35 max |
| Base beneficiary premium (used to calculate penalties) | — | $41.33 |
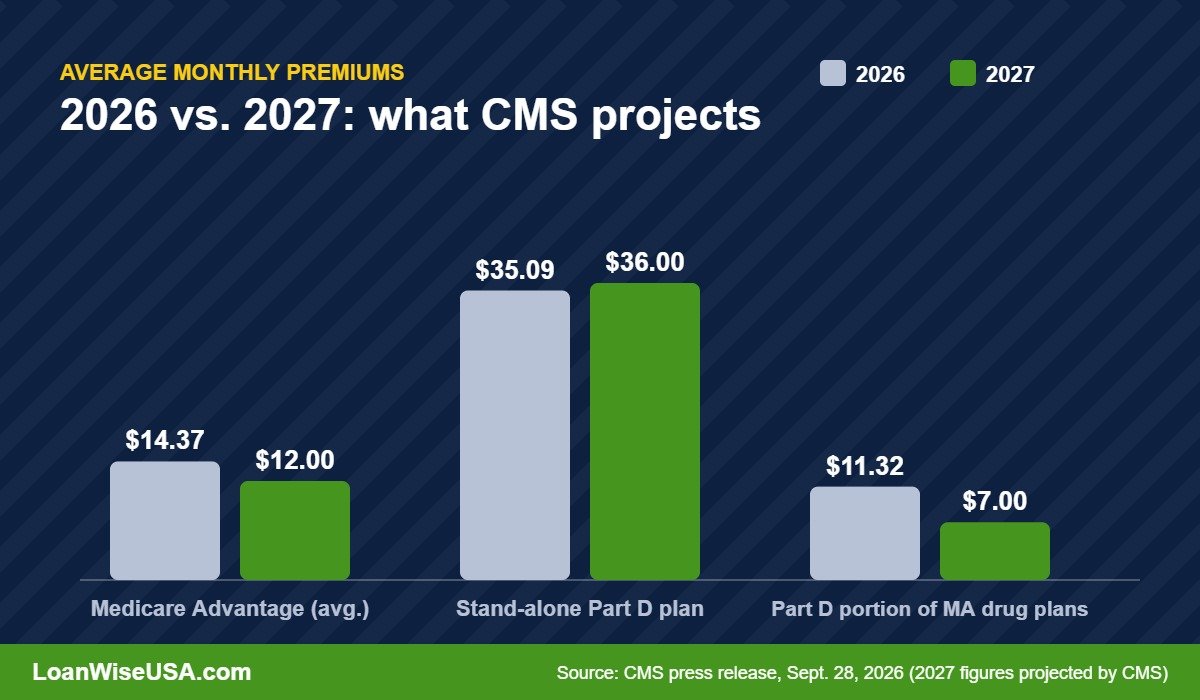
| Average stand-alone drug plan premium | $35.09 | about $36 |
Once your out-of-pocket spending on covered drugs reaches $2,400 in 2027, you pay nothing more for covered Part D drugs for the rest of the year. Plans can set a lower deductible than $700, and some charge none, so the deductible is one of the most useful things to compare.
Does the Medicare Prescription Payment Plan renew automatically?
Yes, in most cases. The Medicare Prescription Payment Plan lets you spread your drug costs into monthly payments across the year, with no interest or fees. Starting with 2027, people who used it in 2026 are automatically re-enrolled if they stay in the same plan. If you switch plans, you need to opt in again with the new plan. This option can help if a big prescription bill lands early in the year. It is a much safer choice than putting pharmacy bills on a credit card or a buy now, pay later plan that can turn into a debt trap.
Are Medicare Advantage premiums going down in 2027?
On average, yes. CMS projects the average monthly Medicare Advantage premium will fall from $14.37 in 2026 to about $12.00 in 2027, a drop of roughly 16.5%. CMS also expects about 34 million people (around 47.4% of everyone with Medicare) to be enrolled in Medicare Advantage in 2027.
An average is not your plan, though. A few other numbers from CMS are worth knowing:
- The number of Medicare Advantage plans dips slightly, from 5,553 to about 5,532.
- More than 99% of people with Medicare have at least one Medicare Advantage plan available, and 97% have 10 or more.
- About 8 in 10 current Medicare Advantage enrollees can stay in their plan for the same or a lower premium.
- The average Part D premium inside Medicare Advantage drug plans (after rebates) falls from $11.32 to about $7.
That still leaves about 2 in 10 enrollees whose current plan is going up in price, changing, or leaving their area. Your plan’s Annual Notice of Change, which plans must mail by September 30, tells you exactly what is different for 2027.
What will Part B cost in 2027?
The 2027 Part B premium and deductible have not been announced yet. CMS usually releases them in the fall. For 2026, the standard Part B premium is $202.90 a month and the deductible is $283. The Medicare Trustees have projected a 2027 premium of about $209.50, but that is a projection, not an official figure.
Part B premiums are usually taken straight out of Social Security checks, so they decide how much of your raise you actually keep. Our guide to the 2027 Social Security COLA of 3.6% and what changes in your check walks through that math.
Should you switch Medicare plans for 2027?
You do not have to switch, but you should check. Plans that were a good fit in 2026 may not be a good fit in 2027. Look closely if any of these apply to you:
- Your Annual Notice of Change shows a higher premium, a higher deductible, or higher copays.
- One of your drugs was dropped from the plan’s formulary or moved to a more expensive tier.
- Your doctor, hospital or preferred pharmacy is leaving the plan’s network.
- Your health or prescriptions changed a lot this year.
- Your Medicare Advantage plan is ending in your county (you will get a non-renewal letter).
The best way to compare is by total yearly cost, not by premium alone. A $0-premium plan with a high deductible and high drug copays can cost more over a year than a plan with a modest premium. It is the same idea behind our look at cost-per-wear math and why the cheapest sticker price isn’t always cheapest.
Original Medicare or Medicare Advantage?
| Feature | Original Medicare + Part D | Medicare Advantage |
|---|---|---|
| Doctors and hospitals | Any provider that accepts Medicare | Usually a plan network (HMO or PPO) |
| Yearly out-of-pocket limit on medical care | None unless you buy Medigap | Yes, set by each plan |
| Drug coverage | Separate Part D plan | Usually built in |
| Extra benefits (dental, vision, hearing) | Generally not covered | Often included, varies by plan |
| Prior authorization | Rarely needed | More common |
One caution: if you leave a Medigap policy to try Medicare Advantage, you may not be able to buy Medigap again later without medical questions, depending on your state. Check your state’s rules before you drop a Medigap policy.
Step-by-step checklist before December 7
- Read your Annual Notice of Change. Note any change to premium, deductible, copays, drug list, and network.
- List your prescriptions. Write down every drug, dose and how often you take it.
- List your doctors and pharmacy. You will check that each one is in network for 2027.
- Use the Medicare Plan Finder. Go to Medicare.gov, enter your drugs and pharmacy, and sort plans by “lowest drug + premium cost.”
- Compare total yearly cost. Add premium x 12, the deductible, and expected copays for each plan you are considering.
- Check star ratings. Medicare rates plans from 1 to 5 stars for quality and service.
- See if you qualify for help. Extra Help (the Part D Low-Income Subsidy) and Medicare Savings Programs can cut premiums and drug costs. Apply through Social Security or your state Medicaid office.
- Get free, unbiased advice if you need it. Your State Health Insurance Assistance Program (SHIP) offers free one-on-one counseling.
- Enroll before December 7. Enroll through Medicare.gov, by calling 1-800-MEDICARE (open 24/7), or directly with the plan. Save your confirmation number.
How do you avoid Medicare open enrollment scams?
Scammers are busiest during open enrollment. Medicare will not call you to sell a plan or ask for your Medicare number. Do not give your Medicare, Social Security or bank details to anyone who contacts you out of the blue. Be wary of TV ads and robocalls that promise “extra benefits” or cash back. When in doubt, hang up and call 1-800-MEDICARE yourself. Also keep an eye on your overall debts: if you have defaulted federal loans, read up on what borrowers in default need to know now, since collections can affect federal payments.
Medicare open enrollment 2027 FAQ
When does Medicare open enrollment end?
It ends on December 7, 2026. Changes take effect on January 1, 2027.
What is the Part D out-of-pocket maximum for 2027?
$2,400 for covered drugs, up from $2,100 in 2026. After you reach it, you pay $0 for covered Part D drugs for the rest of the year.
What is the maximum Part D deductible in 2027?
$700, up from $615. Some plans charge a lower deductible or none.
Is the 2027 Part B premium announced?
Not yet. The 2026 premium is $202.90 a month. CMS usually announces the next year’s amount in the fall.
What happens if I do nothing during open enrollment?
In most cases your current plan renews automatically for 2027, with its new 2027 costs and rules. If your plan is not renewing, you will get a letter explaining your options.
Can I change plans after December 7?
Only in limited cases. Medicare Advantage members can make one change from January 1 to March 31. Special Enrollment Periods apply after certain life events, such as moving or losing other coverage.
Related reading on LoanWiseUSA
- 2027 Social Security COLA Is 3.6%: What Changes in Your Check (and the Scam to Avoid)
- BNPL (Buy Now, Pay Later) Debt Trap: Why More Americans Are Getting Stuck
- Student Loan Defaults Are Back — What Borrowers Need to Know Now
- The Cost-Per-Wear Maths: Why One $250 Jacket Beats Four $60 Ones
Sources
- CMS: Medicare Advantage and Medicare Prescription Drug Programs Expected to Remain Stable in 2027 (Sept. 28, 2026)
- CMS: Calendar Year 2027 Medicare Advantage and Part D Rate Announcement
- CMS: 2027 Part D National Average Monthly Bid Amount and Base Beneficiary Premium (July 28, 2026)
- CMS: 2027 Medicare Advantage and Part D Landscape State-by-State Fact Sheets
- Medicare.gov Plan Finder
- AARP: Medicare Part B premium for 2027 (Oct. 5, 2026)
- Humana: What’s new for Medicare Part D in 2027
Disclaimer: This article is general information, not financial, insurance, or medical advice. Plan costs and benefits vary by plan and location. Confirm details with Medicare.gov, 1-800-MEDICARE, your plan, or a licensed or SHIP counselor before making decisions.

[…] coverage. Medicare eligibility starts at 65 regardless of when you claim Social Security (see our Medicare open enrollment guide), so a spouse retiring earlier may need ACA marketplace coverage until […]